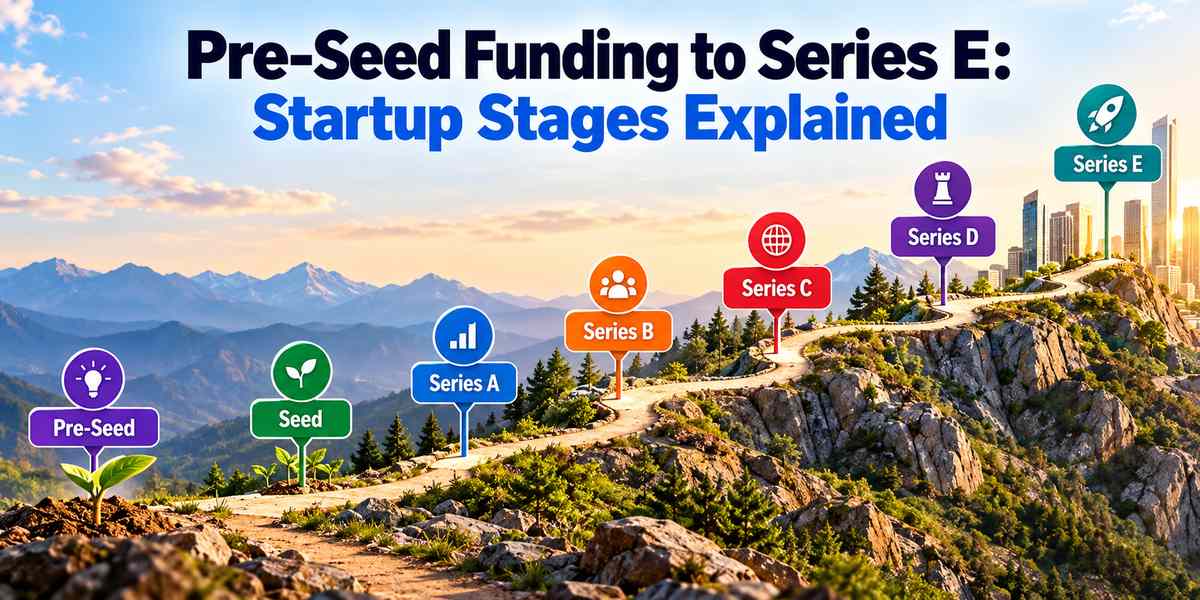

There’s no denying that startup funding has its own confusing language. Pre-seed, seed, Series A, Series B, all the way up to Series E. Then someone drops “unicorn” into the conversation and you’re supposed to just nod along.
I’ve watched a lot of founders nod along. Honestly, I did it myself for years before I actually sat down and figured out what each stage means in practice.
Here’s the thing. The labels aren’t random. Each stage answers a different question for investors, and each one expects different proof from you. Once you see that pattern, the whole ladder makes a lot more sense.
If you’re still at the idea stage, our guide on starting a startup from scratch is a better first read. This piece picks up from the moment you decide to take outside money.
What Is Capital for a Business, Anyway?
Before we get into rounds and letters, let me back up a step. Because a lot of guides skip this part, and I think that’s a mistake.
So, what is capital for a business? It’s the money you use to build and grow the company. Not the cash that pays this month’s bills, but the money that funds the next big step. Hiring, product, marketing, expansion.
Capital usually comes in two forms. Debt, which you pay back. And equity, where you sell a piece of the company instead.
And what is a capital raise? It’s simply the process of bringing that money in from outside. Honestly, it’s less fancy than it sounds. A capital raise can mean a bank loan, a grant, or selling shares to investors. In startup land, though, it almost always means selling equity, and that’s what the rest of this guide is about.
Startup Funding Stages at a Glance
Before the details, here’s the rough map. These are typical 2026 ranges, not rules, and plenty of rounds land outside them.
|
Stage |
Typical Round Size |
What Investors Want to See |
|
Pre-seed |
$250K to $1.5M |
A strong founder and a real problem |
|
Seed |
$2M to $5M |
Early users and signs of demand |
|
Series A |
$10M to $20M |
Repeatable revenue and product-market fit |
|
Series B |
$20M to $60M |
A growth engine that scales |
|
Series C to E |
$50M and up |
Market leadership, expansion, or IPO prep |
Sure, AI startups are blowing past these numbers right now. But for most founders, this table is closer to reality than the headlines.
Pre-Seed Funding: Betting on the Founder
So, what is pre-seed funding? It’s the very first outside money a startup takes. Usually there’s no revenue yet. Sometimes there isn’t even a finished product.
A pre-seed round in 2026 typically lands somewhere between $250K and $1.5M. The money goes toward building a first version, talking to customers, and maybe hiring one or two people.
Pre-seed investors are mostly angels, accelerators, micro-VC funds, and yes, friends and family. They know the odds are terrible. They’re betting on you more than on the idea, which is a slightly scary thing to realize when you’re the one pitching.
Most pre seed capital arrives through SAFEs rather than priced equity. A SAFE is basically a promise of future shares, converted at your next priced round. It’s fast, cheap on legal fees, and easy to set up. The catch? Stack too many SAFEs and the dilution surprise at conversion can hurt.
Pre-seed check sizes vary a lot, and founders often get this wrong. From what I’ve seen, an angel might write a check between $25K and $100K. A dedicated pre-seed fund might put in $250K to $1M and lead the round. So most pre-seed rounds end up stitched together from several smaller checks, not one big one. For an early stage startup, that patchwork is completely normal. Annoying, but normal.
Pre-Seed vs Seed: Where the Line Actually Is
People mix these up constantly. The simplest way I explain pre-seed vs seed is this: pre-seed funds a thesis, and seed funds early evidence.
At pre-seed, a good story and a strong team can close the round. By the seed stage, investors want numbers. Users, retention, maybe some early revenue. The seed stage is where “interesting idea” has to start turning into “this is working.”
Seed Stage: Proving People Actually Want It
A typical seed round now runs $2M to $5M. According to Carta’s recent data on software startups, the median seed valuation sits around $24 million post-money. Founders typically give up roughly 20% of the company at this stage.
That $24M figure sounds exciting. But it’s skewed upward by AI companies raising at huge premiums. A regular SaaS startup without an AI angle will often raise at a lower valuation, sometimes a lot lower.
The seed money usually funds product development, the first real hires, and early go-to-market experiments. This is where early-stage venture capital firms start showing up alongside the angels. In a nutshell, seed is about proving people actually want what you built.
Series A: The Hardest Jump on the Ladder
If there’s one round founders lose sleep over, it’s this one.
Series A startups typically raise $10M to $20M. Carta puts the recent median Series A valuation around $80 million for software companies. Investors at this stage want repeatable revenue, a clear customer profile, and proof the business can grow with more money poured in.
And the bar is high. One analysis of Carta data found only about 15% of startups that raised seed in early 2022 closed a Series A within two years. Back in 2018, that number was roughly double. Investors call it the Series A crunch, and it’s very real.
To illustrate how split the market is, look at the top end. Giant $100 million-plus Series A rounds are hitting record levels this year, and most of those jumbo Series A deals are going to AI companies. So you have a handful of startups raising enormous rounds while thousands of others struggle to raise anything at all.
One more tip here. If you sell to other businesses, look specifically for B2B Series A investors. They understand long sales cycles, pilot deals and annual contracts. A consumer-focused fund might pass just because your growth curve looks slower, even when your business is actually healthier.
Series A vs Series B: What Actually Changes
The simplest way I think about Series A vs Series B is this. Series A asks, “Does this work?” Series B asks, “Can this get big?”
A Series B round typically ranges from $20M to $60M. Carta’s recent median valuation for Series B software companies is around $191 million. That’s a big step up, and the expectations climb with it.
A Series B startup usually has solid revenue, a working sales engine, and a leadership team beyond just the founders. Series B financing tends to pay for expansion: new markets, bigger sales teams, and senior hires. Dilution usually drops a bit here too, often into the mid-teens percentage range.
Time matters as well. Getting from seed to Series B often takes years, not months, which lines up with what I wrote about how long startup success really takes. Patience is a big part of the funding game, whether you like it or not.
Series C, D, and E: Late-Stage Money
Once you’re past Series B, the rounds get bigger and the goals shift again.
Series C
The Series C funding meaning is pretty simple: scale what’s already working, fast. A Series C company usually has strong revenue and is chasing market leadership. Money goes to international expansion, acquisitions, or new product lines. Round sizes often start around $50 million and go well past $100 million.
Series D and Series E
Not every startup needs a Series D. Some raise one because they’re preparing for an IPO. Others raise one because they missed targets and need more runway. Context matters a lot here.
In 2026, AI and deep tech companies with huge compute bills dominate Series D funding. A Series E is rarer still. Companies that reach Series E funding are usually either very large or very capital hungry, and sometimes both.
Much of the late-stage money right now flows into AI, including the enterprise AI agents companies are racing to deploy. Honestly, I think that concentration is the biggest story in venture this year.
What Is a Unicorn Startup, Really?
A unicorn is a private startup valued at $1 billion or more. Investor Aileen Lee coined the term back in 2013, when these companies were genuinely rare. Rare like, well, unicorns.
So what is unicorn status in 2026? Less exclusive than it used to be. AI has minted a fresh wave of them this year. But unicorn in business terms only means a valuation on paper. It doesn’t mean profit, and it doesn’t guarantee a good exit.
In fact, many older unicorns are in trouble. PitchBook data shows the U.S. has around 857 unicorns, and nearly half haven’t raised fresh funding in three years. A lot of those valuations were set during the 2021 boom and simply don’t hold up anymore.
Globally, the U.S. still leads, with Chinese unicorn companies forming the next biggest group. Above the unicorn sits the decacorn, a startup worth $10 billion or more.
How Startup Valuation Works at Each Stage
Startup valuation at early stages is more art than math. There’s often no revenue to multiply, so investors lean on comparables, team quality, and market size.
Common startup valuation methods include:
- Comparable rounds. Investors look at what similar startups raised recently. This is the most common approach at seed and Series A, and it’s why market hype moves prices so much.
- Revenue multiples. Once you have revenue, valuation becomes a multiple of it. AI companies currently get much higher multiples than regular SaaS, which frustrates a lot of non-AI founders.
- Working backward from the round. At pre-seed, valuation is often just the output of how much you raise and how much equity you’re willing to give. Raise $1M for 10%, and you’re a $10M company on paper.
Don’t obsess over average valuation figures you see online. They’re skewed by a few enormous deals. The median, and your own sector’s median, tells you far more.
Other Ways of Raising Capital
Venture capital isn’t the only road. Sure, it gets all the headlines. But plenty of solid companies never raise a single VC round.
Equity crowdfunding. You sell small stakes to lots of everyday investors through regulated platforms. It works well for consumer brands with loyal fans. The main types of crowdfunding are donation-based, reward-based, debt-based, and equity-based, and only the last one gives backers actual ownership.
Revenue-based funding. You get cash upfront and repay it as a share of monthly revenue until you hit an agreed cap. If you’re wondering what is revenue-based financing good for, the answer is companies with steady revenue that don’t want to give up equity.
Bootstrapping. You grow on customer revenue alone. Slower, yes. But you keep control, and if you’re going this route, a lean tool stack matters. I listed a few affordable ones in our piece on tools that make setting up an online business easier.
Honestly, raising capital from VCs only makes sense if your business can grow fast enough to return their fund. Many good businesses simply can’t, and that’s fine.
Grants: Free Money, With Strings
Most founders forget grants exist.
In the US, the NSF Seed Fund (officially called America’s Seed Fund) gives deep tech startups money for research and development. Phase I awards go up to $305,000. Companies that do well can apply for a much bigger Phase II award after that. And the best part? The government takes zero equity.
Sure, there’s a catch. The program froze when its legal authority lapsed in late 2025, and Congress only restarted it in 2026. The paperwork is heavy too. And it only really fits science-heavy companies, not your average app or ecommerce brand.
But if you’re building something genuinely technical, I’d look at it before giving away 20% of your company.
Fundability: Are You Actually Ready to Raise?
Here’s a word I wish more founders understood: fundability. It just means how ready your startup is to attract investment, right now, as it stands today.
Not how good your idea is. How fundable your business looks to someone writing a check.
I’ve seen great products fail to raise because the founders pitched too early. And I’ve seen average products raise easily because everything around them looked solid. Fair? Not really. But that’s how it works.
What Investors Check First
1. The team. Can these people actually build and sell this thing? At the early stages, this matters more than almost anything else.
2. Traction. Users, revenue, retention, waitlists. Any proof that real people want what you built.
3. Market size. Investors need a big enough market to return their fund. A nice niche business often can’t do that, even a profitable one.
4. A clean cap table. Messy ownership, too many tiny investors or a co-founder who left with 30% can scare people off fast.
Build a Funding Strategy Before You Pitch
A funding strategy is your plan for how much to raise, from whom, and what it gets you. Without one, you just end up pitching everyone and hoping.
Mine would cover three things. How many months of runway the round buys. Which milestones it needs to hit before the next round. And which type of investor fits your stage.
That last point saves a lot of time. An early stage VC wants a different story than a growth fund does. Match the pitch to the room, and your fundability goes up without changing anything about the product.
How to Find Investors Without Wasting a Year
This is the question I hear most, so here’s my short answer on how to find investors.
Start with warm intros. A referral from another founder or a mutual contact beats a cold email almost every time. Then target investors who actually fund your stage and sector. Early-stage VC firms that write pre-seed checks won’t lead your Series C, and vice versa.
Set a clear funding target before you start. Know exactly how much you need, what it buys, and how many months of runway it gives you. Investors also check your total raised to date, so be ready to explain every earlier round.
A few quick tips if you’re looking for investors right now:
- Keep the process tight. Capital raising drags on when founders pitch one investor at a time. Batch your meetings into a few weeks to build momentum.
- Show traction, not just vision. In 2026, even seed investors want numbers. Bring whatever metrics you have.
- Know your walk-away terms. Decide your minimum valuation and maximum dilution before the pressure hits.
That’s really the core of how to raise capital well. Preparation beats charm, most of the time.
Where Startup Funding Goes Next
I think the gap between AI and everyone else will keep widening for at least another year. Mega-rounds will keep grabbing headlines, and the Series A crunch won’t disappear overnight.
But here’s my honest take. The founders who win won’t be the ones who raise the most. They’ll be the ones who raise the right amount at the right stage and then actually hit the milestones for the next one. Everything else is just noise and press releases.